A restricted gift is a promise. A funder hands over money for a stated purpose, and the organization agrees to spend it only on that. The accounting for it is not complicated. Keeping that promise, transaction by transaction, through a year of ordinary spending, is where it gets hard.
Fund accounting is the tool built for that job. It sorts money by the strings attached to it, so an organization can answer the question that matters most in the sector: not "did we have the cash," but "were we allowed to spend it on that."
Most guidance on this stops at the bookkeeping. The entries are worth knowing, and this covers them. But the entries are not what goes wrong. What goes wrong is the spend, on an ordinary Thursday, against a fund nobody checked. So this is as much about controlling restricted money as recording it.
What is nonprofit fund accounting? Nonprofit fund accounting is a method of tracking money by the restrictions attached to it rather than as a single pool. Each gift is classified by its donor or grant conditions, recorded in the matching net asset class, tracked as a separate fund for the life of the restriction, and released only when the stated purpose is met. It exists because nonprofits must prove not just that the numbers balance, but that every dollar was spent as promised, on the public record of a 990 or T3010.
Key takeaways
- Restricted funds are donor- or grant-designated money whose terms are legally enforceable; misusing them can mean repaying the grant, losing future funding, an audit finding, and reputational damage.
- Fund accounting classifies money by restriction and follows three steps — record it in the right net asset class, track it separately, release it when the restriction is met — but the accounting alone does not stop the money being spent wrongly.
- The missing control is at the point of payment: routing each payment against its fund and requiring approval before release keeps restricted money where it belongs, and produces the evidence a 990 or T3010 audit asks for.
Restricted, unrestricted, and permanently restricted funds
Fund accounting sorts incoming money into three classes, set by whoever gave it.
Unrestricted funds. Money the organization can use for any legitimate purpose. General donations, unrestricted grants, earned income. This is the money that keeps the lights on, and the only pool with real flexibility.
Temporarily restricted funds. Money tied to a purpose or a time. A grant for a specific program, a gift for a capital project, a donation that must be spent next year rather than this one. The restriction lifts once the condition is met, and the money moves to unrestricted.
Permanently restricted funds. Money that must be held in perpetuity, most often an endowment, where the principal is kept intact and only the income it generates can be spent, usually for a stated purpose.
The restriction is set by the funder at the moment of the gift, and it is legally enforceable. That is the part that makes this more than a labeling exercise. Spending a temporarily restricted grant on the wrong program is not an accounting slip. It is a broken agreement.
Where restricted funds actually go wrong
The failures in restricted-fund management are rarely dramatic, and rarely dishonest. They are quiet, and they happen at the point of spending rather than the point of recording.
A shared cost, rent or a salary, gets charged wholly to one grant because that fund had budget left, when it should have been split across programs. A payment goes out against a restricted fund because the person approving it did not know the fund was restricted, or did not check. A grant condition, spend by a certain date, quietly lapses because nobody was watching the calendar against the balance.
None of these require bad intent. They come from an overloaded team spending quickly, with the restriction living in a grant agreement in someone's inbox rather than in the moment the payment is approved.
The consequence is what makes it serious. Misusing or under-reporting a restricted fund can mean repaying the money, losing the remainder of the award, ineligibility for future grants from that funder, a finding in the audit, and the reputational damage that follows a funder feeling let down. One misallocated cost can cost far more than its own value.
Related reading: internal controls for nonprofits
How to account for restricted funds: record, track, release
The bookkeeping itself follows three steps, and they are worth getting right.
Record. When the gift arrives, classify it by its restriction and recognize it in the correct net asset class. Under current standards the income is recognized when the commitment is unconditional, in the year it is promised, regardless of when the related spending happens. Capture the restriction in writing at this point, from the grant agreement or gift letter, not from memory.
Track. Hold each restricted fund as a separate line for the life of the restriction. Every expense charged against it reduces that balance. This is the discipline that lets you answer, at any moment, what came in, what has been spent, and what remains, for each fund rather than in aggregate.
Release. When the restriction is satisfied, the purpose delivered or the time elapsed, release the funds from restricted to unrestricted. This is a reclassification, recorded as it happens, so the financial statements show restrictions lifting in step with the work.
Done properly, this produces a schedule for every restricted fund on demand, which is exactly what an auditor and a funder will ask to see.
The control the accounting misses
Here is the gap that every explainer of fund accounting leaves open. All of the above is a record of what happened. None of it stops the wrong thing happening in the first place.
The ledger records what happened. It doesn't stop it.
By the time an overspent restricted fund shows up in the accounts, the money has already left. Control means the check runs at the point of payment, not after.
The ledger tells you, after the fact, that a restricted fund was overspent. It does not stand between the payment and the fund at the moment of approval. By the time the misallocation shows up in the accounts, the money has already left.
That is the difference between recording restricted funds and controlling them. Control means the check runs at the point of payment: the fund is identified when the spend is requested, the payment routes to someone with the authority to approve against that fund, and it cannot proceed until they have. The restriction stops being a note in an agreement and becomes a rule the transaction has to pass.
This is the layer most nonprofits are missing. They have the fund accounting. What they lack is the mechanism that makes the restriction bite on a Thursday afternoon, when a busy approver is clearing a queue and has no way of knowing which fund a bill should be drawn against.
Learn more: approval workflows and audit and fraud control
Fund tracking in QuickBooks and Xero on a small team
You do not need dedicated fund accounting software to do this well. Most small and mid-sized nonprofits run on QuickBooks Online or Xero, and both can track restricted funds with the structure already in them.
In practice that means using classes, locations, or tracking categories to tag every transaction to its fund and program, so income and spending can be reported by fund rather than only by account. It means a chart of accounts that keeps restricted and unrestricted activity legible. And it means tagging the fund at the point the spend is entered or requested, not reconstructing it at month end.
The limit of both platforms is the same one the accounting has: they record the fund a transaction was assigned to, but they do not enforce approval against it before the money moves. On a small team, where the person entering a bill is often the person paying it, that enforcement is exactly what is missing.
How restricted-fund discipline makes you audit-ready
Restricted funds are one of the first things a nonprofit audit examines, because they are where entitlement to spend is tested most directly. An auditor wants to see, for each fund, what came in, what was spent, on what, and with whose authorization.
A team that tags spend to funds and records approvals as they happen produces that evidence from records it already holds. A team that does not spends the weeks before fieldwork rebuilding it, and hopes the reconstruction holds up.
The same discipline answers the public return. Both the US Form 990 and the Canadian T3010 ask how the organization handles and oversees its money, on the record. Restricted-fund tracking done continuously is a large part of that answer, prepared without a filing-season scramble.
Related reading: how to prepare for a nonprofit audit
How ApprovalMax helps
The pattern we see most in nonprofit finance is not dishonesty. It is a restriction that lived in a grant agreement and never made it into the moment a payment was approved.
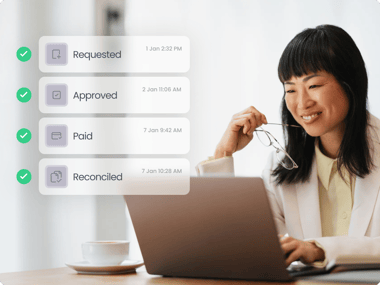
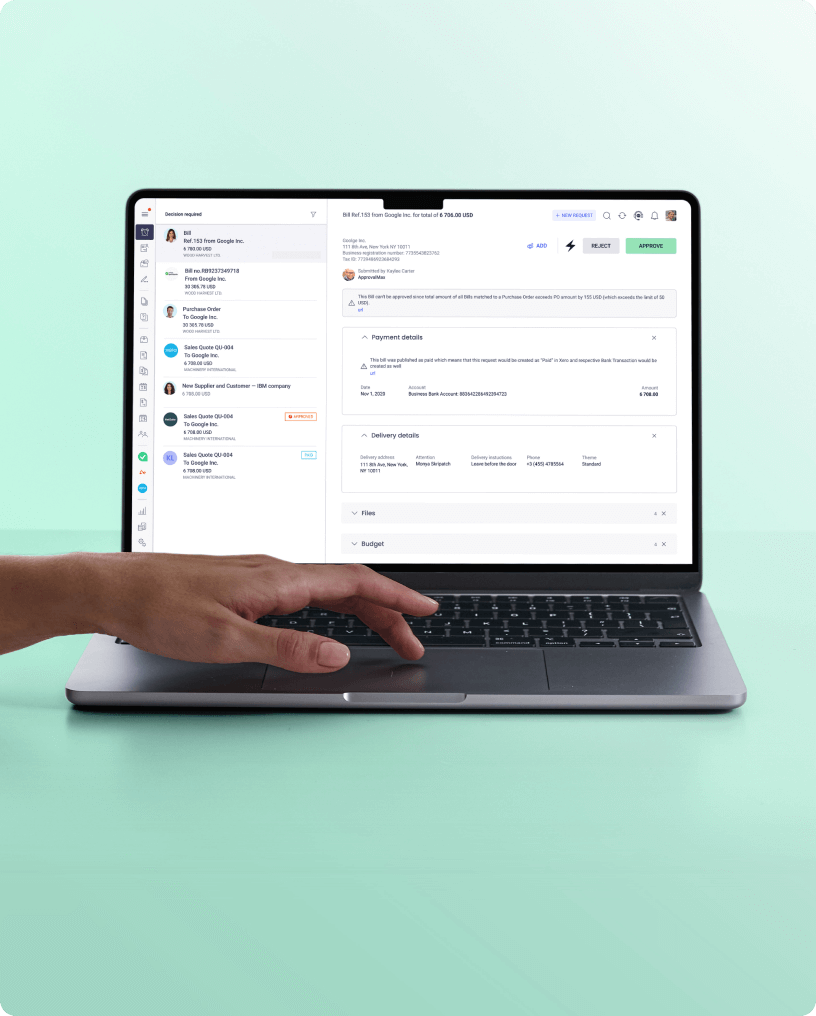
ApprovalMax sits on top of QuickBooks Online and Xero and enforces the approval step the accounting platform leaves open. Bills and expenses route to the right approver by amount, fund, or program, so a payment against a restricted fund reaches someone with the authority to approve it and cannot proceed until they do. Every decision is captured with a timestamp and a name.
The result is that the restriction is checked before the money leaves, not discovered after, and the schedule an auditor asks for exists as a byproduct of working normally.
Free trial
See how ApprovalMax keeps restricted funds where they belong
No credit card required. Works with Xero, QuickBooks Online, and NetSuite.
Start free trial
Book a demo
Where to start
The fastest way to find out whether your restricted funds would hold up is to check your process against what an auditor or a funder actually asks for.
It walks through restricted-fund tracking, segregation of duties, approval thresholds and audit-trail completeness, with the small-team version of each.
You can also watch our session Built to be audited: spend control for nonprofits on demand. It covers what auditors and funders look for, how to enforce segregation of duties on a small team, and how to keep restricted money where it belongs all year.
Frequently asked questions
What is nonprofit fund accounting?
It is a method of tracking money by the restrictions attached to it rather than as one pool. Each gift is classified by its donor or grant conditions, recorded in the matching net asset class, tracked as a separate fund, and released when the stated purpose is met.
What is the difference between restricted and unrestricted funds?
Unrestricted funds can be used for any legitimate purpose. Restricted funds carry conditions set by the funder, on purpose or timing, that are legally enforceable and must be tracked for the life of the gift.
What are temporarily and permanently restricted funds?
Temporarily restricted funds are tied to a purpose or a time and become unrestricted once the condition is met. Permanently restricted funds, typically endowments, must be held in perpetuity, with only the income spent.
Can you do fund accounting in QuickBooks or Xero?
Yes. Both track restricted funds using classes, locations, or tracking categories to tag transactions by fund and program. What neither does on its own is enforce approval against the correct fund before a payment is made.
What happens if a nonprofit misuses restricted funds?
It can mean repaying the money, losing the rest of the award, becoming ineligible for future grants from that funder, a finding in the audit, and reputational damage. Most misuse is accidental, which is why controlling spend at the point of payment matters.
How do restricted funds affect a nonprofit audit?
They are examined closely, because they test whether the organization was entitled to spend as it did. Auditors want a schedule for each fund showing what came in, what was spent, and who authorized it, which continuous tracking produces without a scramble.





 Ask Perplexity